Investment Banking in France: What a Banque d'Affaires Does, the Teams, the Banks in Paris and How to Read the League Tables
- Investment Banking
- Careers
Investment banking in France runs through the banques d'affaires: firms that advise companies, funds and governments on M&A, IPOs, debt raising and restructurings and, in the strict sense, hardly lend at all. Below: banque d'affaires vs investment bank, the French words on job ads, the teams (M&A, ECM, DCM, leveraged finance), the banks in Paris by category, how to read the 2025 league tables, the average deal size per adviser, and how to get in.
Goldman Sachs or Rothschild & Co: which was France's top investment bank in 2025? Both. In LSEG's M&A advisory ranking for France, Goldman Sachs came first by value, credited with $73bn of deals, and Rothschild & Co came first by number of deals, with 150, close to four times as many (Les Echos, December 31, 2025). That detail sums up investment banking in France: under the same French label, banque d'affaires, one firm can advise on a few giant deals and another on dozens of smaller ones, and it isn't the same job.
This guide is for students, French or not, who are aiming at an investment banking internship or job in Paris. It explains what a banque d'affaires is and the French words you'll meet on job ads, the teams inside a bank, the firms in Paris by category, how to read the 2025 league tables, and how to get in. It relies on primary sources opened between October 28 and November 16, 2026: the French Monetary and Financial Code (code monétaire et financier) on Légifrance, the Vernimmen corporate finance glossary, the career sheets of the Apec (the French executive employment agency) and France Travail (the public employment service), pages from Lazard, Rothschild & Co, BNP Paribas, Barclays and Société Générale, and six rankings, plus a 2015 interview with a Paris banker published by Mergers & Inquisitions. When a source is behind a paywall, we only use what can be read for free, and we say so. Quotes from French sources are our translations.
Investment banking in France in two sentences
In everyday use, a banque d'affaires advises its clients on their financial deals: selling or buying a company, listing on the stock market, raising equity or debt, restructuring a balance sheet. The Vernimmen glossary describes it as an intermediary in financial transactions (IPOs, capital increases, bond placements, mergers and acquisitions) that "hardly lends at all"; in it, the banquier d'affaires advises company leaders on a merger or an acquisition and runs the deal through to completion, sums up the Apec in its "M&A advisory banker" sheet.
The word covers two kinds of firms. Lazard calls itself an "independent advisory firm" that "only offers advice and does not offer lending services", and adds, in the FAQ of its London recruitment: "In other banks, this division is often called the Investment Banking Division." The French press also calls the big US banks banques d'affaires: La Tribune writes about "the big American banques d'affaires based in Paris", meaning Goldman Sachs, Morgan Stanley, JP Morgan and Citi (article of September 7, 2026). So when a French source says banque d'affaires, read "investment bank" in the advisory sense.
Banque d'affaires, investment bank, deposit bank: the table
| Banque d'affaires, in the strict sense | Investment bank | Deposit bank (banque de dépôt) | |
|---|---|---|---|
| What it does | Advises and acts as an intermediary: IPOs, capital increases, bond placements, M&A (Vernimmen) | Adds to advice: capital raising, financing and risk management (Barclays) | Makes loans and takes sight and term deposits from the public (definition in the 1945 law, repealed in 1984) |
| Does it lend? | "Hardly at all" (Vernimmen). Lazard: advice only, no lending services | Yes. At BNP Paribas, the leveraged finance team underwrites leveraged loans and high-yield bonds | Yes: lending is, with deposits, its main business (1945 law) |
| Clients | Company leaders, investment funds, institutional investors, public bodies; rarely individuals (Apec) | Companies, governments and financial institutions (Barclays) | The public, who deposit their money with it (1945 law) |
| Examples given by the source | Lazard; Rothschild & Co, "The global independent adviser" | Barclays; BNP Paribas, whose Global Banking division combines financing, cash management and financial advisory | The 1945 law nationalizes (article 6) Crédit Lyonnais, Société Générale, the Comptoir national d'escompte de Paris and the Banque nationale pour le commerce et l'industrie; Title III, which sets the terms, is headed "Nationalization of the large deposit banks" |
Sources: Vernimmen glossary; Apec "M&A advisory banker" sheet; Lazard's London recruitment FAQ; Barclays' Capital Markets internship offer in Paris and BNP Paribas' analyst offer in New York; Law No. 45-15 of December 2, 1945, on Légifrance. All read on October 28, 2026.
The Vernimmen also notes that a banque d'affaires needs less equity capital than a commercial bank.
The French words you'll meet on job ads
If you apply in Paris, offers, rankings and career pages will mix French and English. Here is what each term means, with the source that uses it.
| French term | What it means | Where you'll see it |
|---|---|---|
| Banque d'affaires | The advisory firm, or the advisory side of a bank: what English speakers call investment banking in the M&A sense | Vernimmen, Apec, the French press |
| Banque de financement et d'investissement (BFI), or CIB | A corporate and investment bank, which lends as well as advises: Crédit Agricole CIB calls itself "the corporate and investment bank of the Crédit Agricole Group" | Crédit Agricole CIB's website |
| Banquier d'affaires, banquier conseil M&A | The investment banker who advises on a deal; the Apec also lists analyst M&A and associate M&A as titles | Apec |
| Fusions-acquisitions | Mergers and acquisitions | Les Echos, on the LSEG ranking |
| Chargé d'affaires bancaires | A commercial banker who looks after business clients and puts together their loan applications: not investment banking | France Travail, sheet C1203 |
| Stage off-cycle | An internship outside the summer window; at Barclays in Paris, 3 to 6 months | Barclays' Capital Markets offer |
| Bac+5 | Five years of higher education after the French baccalauréat, master's level | Apec |
| TPE-PME-ETI | French size labels for very small, small and medium, and intermediate-sized companies: in practice, the small- and mid-cap market | Fusacq's ranking |
Pure advisory firm or investment bank?
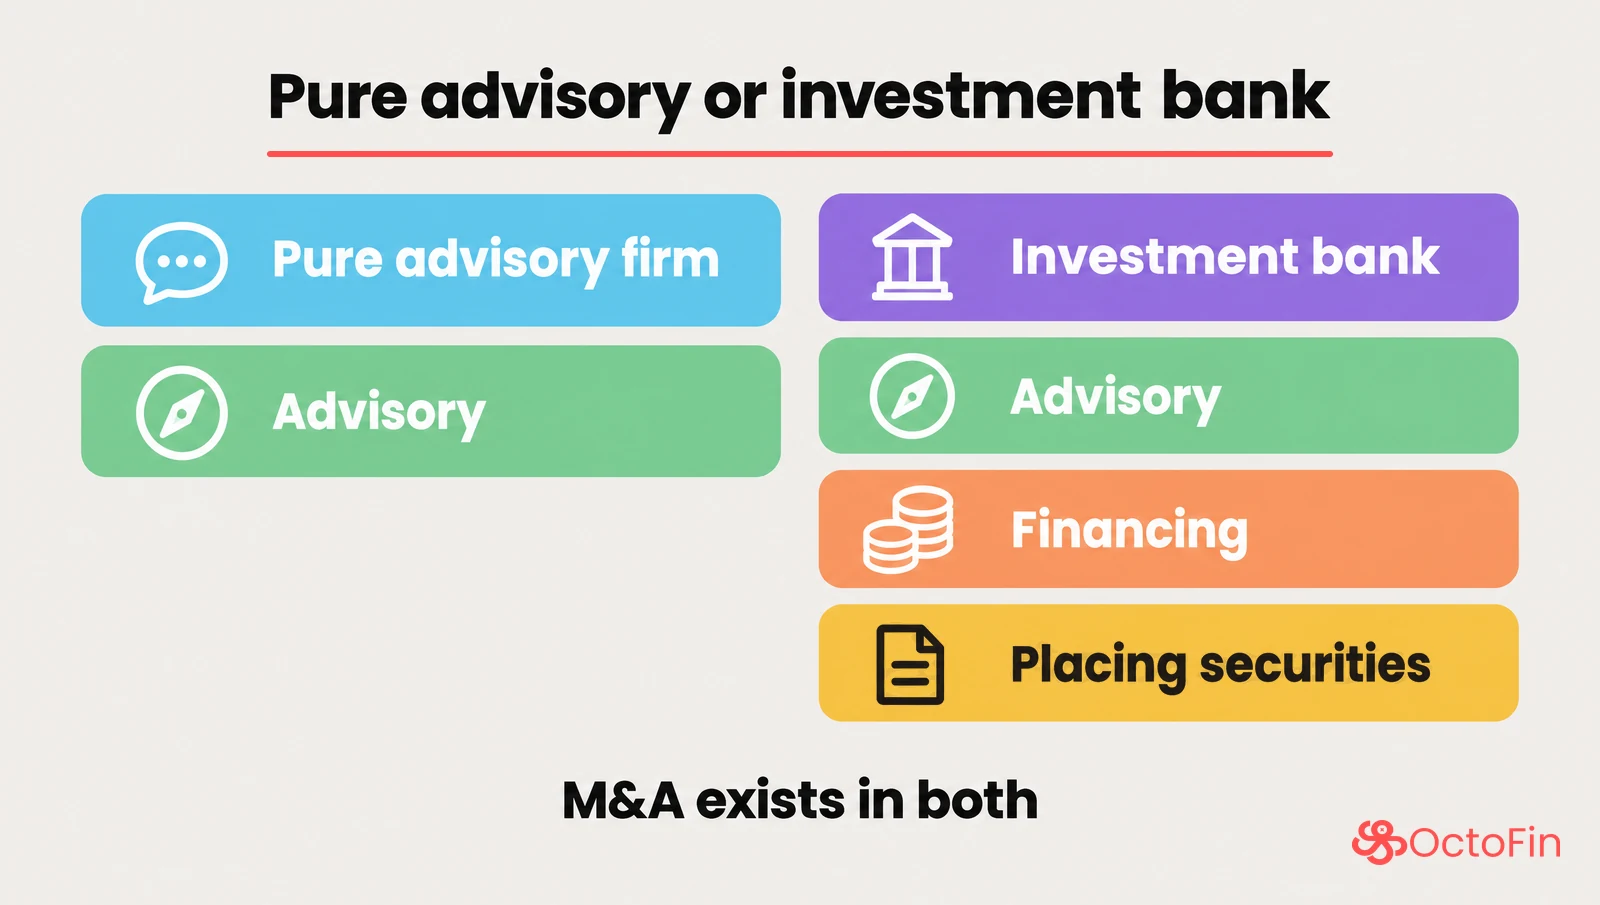
In practice the two terms overlap, and Lazard says so itself: what it calls Financial Advisory is called Investment Banking elsewhere. The difference that matters for your application lies elsewhere. A pure advisory firm, like Lazard, only advises. An investment bank adds teams that finance and place securities: at Barclays in Paris, the Capital Markets division brings together debt capital markets (DCM), equity capital markets (ECM), leveraged finance and syndicate (internship offer read on October 28, 2026). M&A exists in both: its entry-level job is described in our guide to the M&A analyst.
How to read the league tables for France
Search for the top investment banks in France and you'll find lists that contradict each other. They aren't necessarily wrong; they don't count the same thing. Here are six rankings, opened between October 28 and November 16, 2026, with what each one measures.
| What the ranking counts | Who comes first, according to the source | Know this before you quote it | Source |
|---|---|---|---|
| Value of the deals advised on | Goldman Sachs: $73bn of deals in France in 2025 (LSEG); $97,629m across 33 deals (Mergermarket, document posted online by PwC) | The leader can change in the last days: Goldman Sachs took the lead on the home stretch, with close to $20bn credited between mid-December and the end of December (Les Echos). It's the value of the deals, not the bank's revenue | Les Echos, December 31, 2025, LSEG ranking (subscribers only: standfirst and two paragraphs readable); Mergermarket, rankings as of January 3, 2026 |
| Number of deals | Rothschild & Co: 150 deals, "nearly 4 times more than Goldman Sachs" (LSEG); 139 (Mergermarket) | A small deal counts as much as a large one | Same sources |
| Number of mandates | The headline names Rothschild, Adviso and EdR CF; 2,599 mandates in total in 2025, according to Training You, a French interview-prep company that reports these league tables | Drawn from three CFNEWS databases, with activity "supported by smid-cap deals and build-ups", says the standfirst; the detail is for subscribers | CFNEWS, March 20, 2026, updated June 6, 2026 (headline and standfirst readable); Training You, March 25, 2026 |
| Tiers awarded by Leaders League | "Incontournable" (top tier): Centerview Partners, Lazard and Rothschild & Co, in M&A for retail and consumer goods (2024 edition) | Five tiers, alphabetical order within each; firms fill in a submission form and confidential interviews are held, plus feedback from peers and third parties | Leaders League, 2024 ranking and methodology page |
| Combined revenue of the companies acquired, in the small- and mid-cap market (TPE-PME-ETI) | Largillière Finance: 25 deals, €362,700k | To appear, an adviser must be listed in Fusacq's directory of experts and publish its deals there | Fusacq, 2025 rankings (final) |
| What candidates think | Goldman Sachs, J.P. Morgan, Rothschild & Co (large-cap M&A in Paris) | Head-to-head votes in a contest run on the Instagram page @StaffingShiit; Crack-It, a French interview-prep company, says its ranking doesn't claim to measure league-table performance | Crack-It, published July 3, 2026, updated October 26, 2026 |
What the gaps tell you
Value or number: two leaders in the same year. LSEG and Mergermarket, two market data providers, agree on the order: Goldman Sachs first by value, Rothschild & Co first by number. They don't agree on the figures: $73bn against $97.6bn for Goldman Sachs, 150 deals against 139 for Rothschild & Co. One possible explanation: they don't necessarily count the same deals, and they weren't closed on the same date (Les Echos article of December 31, 2025; Mergermarket rankings as of January 3, 2026). Mergermarket spells out its rules: a deal counts if the target, the buyer or the seller is in the country; lapsed or withdrawn bids are excluded; a threshold applies ("over 5% or USD 50m", in the document's words). LSEG's criteria aren't in the part of the article readable without a subscription.
Self-reported rankings. Fusacq says it plainly: to appear, you must be listed in its directory and publish your deals there. Leaders League starts from a form filled in by the firms and from interviews, cross-checked with peers and third parties; its ranking page even invites firms to "join the ranking". An adviser missing from Fusacq isn't necessarily inactive: it may simply not publish its deals there.
Perception isn't activity. The ranking published by Crack-It measures what voters on the Instagram page @StaffingShiit remember when they have to choose between two large-cap M&A banks in Paris. It tells you what candidates think, not what a bank does.
In an interview, if you quote a ranking, give its source, its year and what it counts: "In 2025, in France, Goldman Sachs was first by deal value according to LSEG, and Rothschild & Co first by number of deals."
Worked example: how big is the average deal, from large cap to small cap
One division is enough to see that two investment banks in France don't do the same work: the value of the deals advised on, divided by their number. You need a source that gives both numbers. Mergermarket's France 2025 rankings do; for the small- and mid-cap market, Fusacq's ranking also gives both, but with a different yardstick. The LSEG ranking doesn't work here: the readable part of the Les Echos article gives Goldman Sachs' value and Rothschild & Co's deal count, never both for the same bank.
Step 1: the Mergermarket numbers
Eight advisers from Mergermarket's France 2025 ranking (as of January 3, 2026, deals up to December 31, 2025), picked from the categories on this page: US banks, French banks, independent firms, an audit and advisory firm (KPMG, which describes itself that way on its French website), and two firms with many deals of lower value.
| Adviser | Value of deals advised on ($m) | Number of deals |
|---|---|---|
| Goldman Sachs | 97,629 | 33 |
| JPMorgan | 84,289 | 28 |
| Rothschild & Co | 82,176 | 139 |
| Lazard | 63,351 | 52 |
| BNP Paribas | 43,283 | 56 |
| KPMG Corporate Finance | 11,067 | 81 |
| Edmond de Rothschild | 3,539 | 60 |
| Cambon Partners | 2,243 | 35 |
Step 2: the average value per deal
Divide the value by the number of deals, and round only at the end.
| Adviser | Calculation ($m) | Average value per deal |
|---|---|---|
| JPMorgan | 84,289 / 28 ≈ 3,010 | about $3.0bn |
| Goldman Sachs | 97,629 / 33 ≈ 2,958 | about $3.0bn |
| Lazard | 63,351 / 52 ≈ 1,218 | about $1.2bn |
| BNP Paribas | 43,283 / 56 ≈ 773 | about $0.8bn |
| Rothschild & Co | 82,176 / 139 ≈ 591 | about $0.6bn |
| KPMG Corporate Finance | 11,067 / 81 ≈ 137 | about $137m |
| Cambon Partners | 2,243 / 35 ≈ 64 | about $64m |
| Edmond de Rothschild | 3,539 / 60 ≈ 59 | about $59m |
Read the table both ways. Rothschild & Co has about four times as many deals as Goldman Sachs (139 / 33 ≈ 4.2), for an average deal about five times smaller (2,958 / 591 ≈ 5.0). Between Goldman Sachs and Cambon Partners, the average deal drops from about $3bn to $64m, about 46 times less (2,958 / 64 ≈ 46). And the corporate finance arm of an audit and advisory firm, KPMG Corporate Finance, ranks second by number of deals in this France 2025 table, with 81, for an average deal of about $137m.
Step 3: small cap, with Fusacq's yardstick
Fusacq doesn't rank advisers on deal value, but on the combined revenue of the companies acquired, in the small- and mid-cap market. For its number one in 2025, Largillière Finance: 362,700 / 25 = 14,508 (in €k), so about €14.5m of revenue per company acquired, on average.
That isn't a price: what a company is worth depends on its profitability and on the multiple paid, not on its revenue alone. So this figure can't be compared directly with Mergermarket's. But the scale is no longer the same: we're talking about companies with €14.5m of revenue on average, not deals worth billions of dollars. The ranking also includes deals with no amount: Crédit Agricole Midcap Advisors appears with 7 deals and €0k.
What it means for you
Same label, different job. The Apec separates "mega deals", mostly involving listed companies and with a regulatory side, from mid- and small-cap deals on small and mid-sized companies, where the advisory banker competes with small specialist firms, the M&A boutiques. It also gives size markers: €100m of enterprise value for mid cap, €5m at least for small cap. The Paris banker interviewed by Mergers & Inquisitions says the same thing in his own words: a "big emphasis on middle-market deals" in France, with mid-market teams even at bulge bracket banks, and an average deal size that he thinks is probably smaller than in the US (interview published in February 2015). The table above puts numbers on the French side of that. Before you pick your target banks, pick your segment. In an interview, "why large cap?" or "why mid-cap?" is prepared with these orders of magnitude.
The limits of the calculation
- An average isn't a typical deal: a single giant deal pulls the average up.
- Deals with no public value: the Mergermarket document doesn't say how it treats them. If it counts them in the number without giving them a value, the true average is higher.
- Two yardsticks, two currencies: Mergermarket counts deal value in dollars, Fusacq the revenue of the companies acquired in euros.
- One scope, one year: 2025 deals where the target, the buyer or the seller is in France.
The teams in a French investment bank
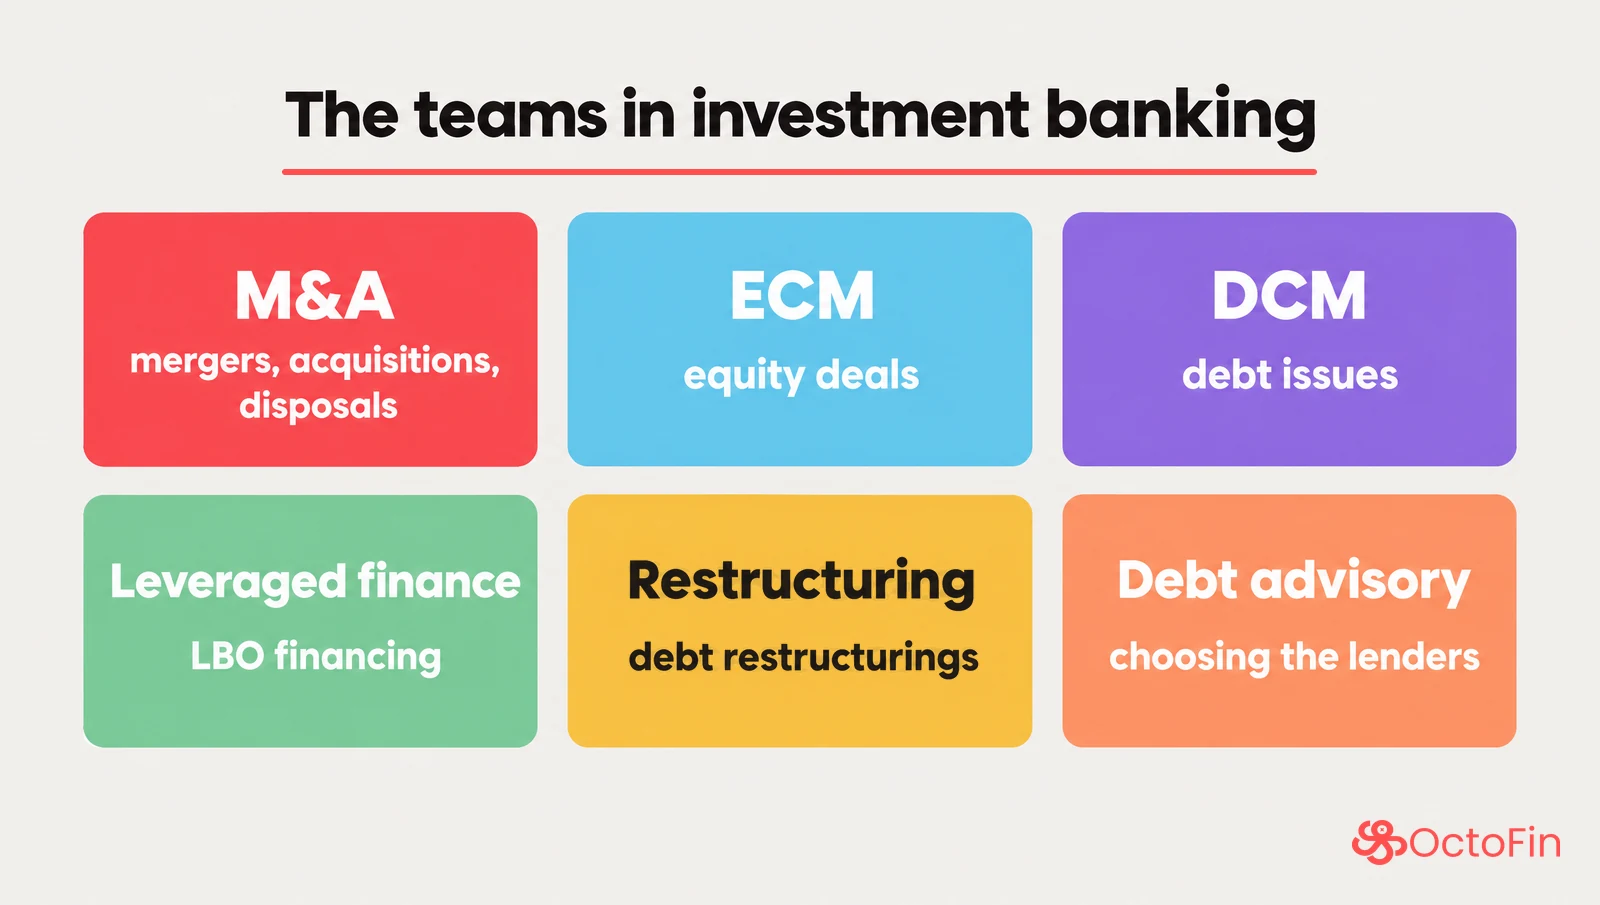
M&A isn't the only job in investment banking. Lazard files under its advisory business M&A and strategic advisory, restructuring, capital structure advisory (including debt advisory and ECM) and private capital advisory. An investment bank like Barclays adds, in its Capital Markets division, DCM, ECM, leveraged finance and syndicate. Here is what each team does, according to the banks' pages read on October 28, 2026.
| Team | What it does | For whom | According to |
|---|---|---|---|
| M&A | Advises on a merger, an acquisition or a sale, and runs the deal through to completion | Company leaders, funds, institutional investors | Apec |
| ECM (equity capital markets) | Originates, structures, underwrites and executes equity deals: IPOs, follow-on offerings, private placements, spin-offs | Issuers, funds, founders, venture capital funds | BNP Paribas (New York offer) |
| DCM (debt capital markets) | Helps issue debt securities: choice of issue (maturity, fixed or floating rate, currency), market conditions, rating advice | Governments, financial and non-financial companies | Société Générale |
| Leveraged finance | Underwrites leveraged loans and high-yield bonds, structures LBO and acquisition financing, advises non-investment-grade issuers | Investment funds and companies | BNP Paribas (New York offer) |
| Restructuring | Recapitalizations, debt restructurings, debt-for-equity swaps, Chapter 11 and other formal proceedings, sovereign debt | Companies, funds, creditors, governments | Rothschild & Co |
| Debt advisory | Advises the borrower on its capital structure and its choice of lenders | The borrower | Rothschild & Co, Lazard |
M&A
M&A means advising a seller or a buyer: valuing the company, finding the other side, running the process and helping negotiate. The Apec's sheet on the M&A advisory banker lists watching clients and their markets, running the process, structuring the financing of the acquisition and following the deal to closing. The entry-level role, its tasks, a sell-side mandate step by step and a worked example are in our guide to the M&A analyst.
ECM: equity deals
The equity capital markets team works on its clients' share capital. At BNP Paribas, it originates, structures, underwrites and executes equity deals for issuers, funds, founders and venture capital funds: IPOs, follow-on offerings after the IPO, private placements and spin-offs (New York analyst offer, updated September 30, 2026, read on October 28, 2026 and taken down since). At Lazard, ECM sits within capital structure advisory: Lazard says it only advises. Under French law, underwriting or placing securities is an investment service: the Monetary and Financial Code lists firm-commitment underwriting and placement, guaranteed or not (article L. 321-1).
DCM: bond issues
Banks' debt capital markets departments help their clients issue debt securities on the markets, writes Société Générale in its financial glossary. The bank advises on the type of issue (maturity, fixed or floating rate, type of bond, currency), reports on market conditions and the market's capacity to absorb the issue, and can advise on credit ratings. Issuers are governments and companies, financial or not, and a standard issue is "around €500m", according to the same glossary. The difference with a loan: a bond has several lenders, the investors who buy it, and its rate is set by the market, not by the bank.
Leveraged finance: the debt behind LBOs
The leveraged finance team finances highly leveraged deals, starting with LBOs, buyouts funded largely with debt. At BNP Paribas, it structures, originates, underwrites and executes deals on the leveraged debt markets for investment funds and companies: underwriting leveraged loans and high-yield bonds, structuring LBO or acquisition financing, liability management, capital structure advice for non-investment-grade issuers (New York analyst offer, read on October 28, 2026). The funds it finances are the ones described in our guide on how to get into private equity, and the job itself has its own guide: leveraged finance, the job, the internship and the interview.
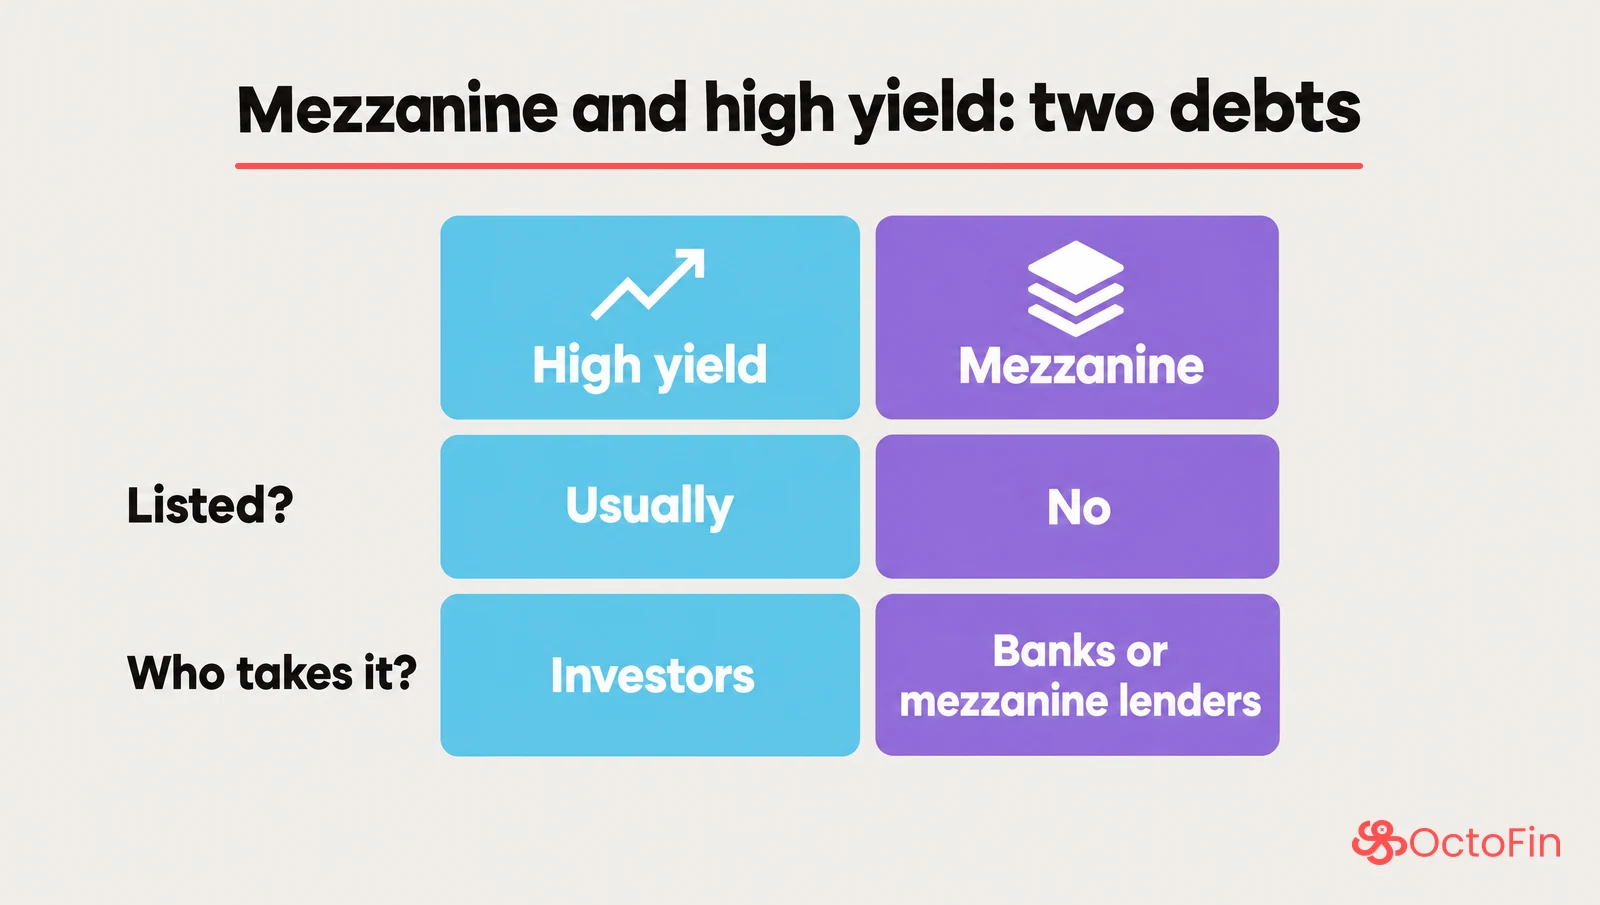
Mezzanine isn't a high-yield bond. The Banque de France defines mezzanine as the financing that sits between equity and senior debt. It is only repaid once the senior debt has been repaid in full; it usually lasts 7 to 10 years; it is taken by banks or by specialist investors, the mezzanine lenders (mezzaneurs), most often as bonds with equity warrants attached (sheet 431, April 2022 version). The Vernimmen (chapter 49) separates the two forms of subordinated debt: high-yield bonds, usually listed, kept for the largest LBOs because, to offer investors enough liquidity, their issues don't go below €150m; and mezzanine, often in bond form but unlisted, taken by specialist funds. Two different debts, then: one usually listed and sold to investors, the other unlisted and subscribed by banks or by mezzanine lenders.
How an LBO is built, debt by debt, is explained in our guide what is an LBO, with a worked example, and question 22 of our investment banking interview questions puts all these debts in one table.
Restructuring: when the debt no longer works
Restructuring advises a company, or those who lent to it, when its debt becomes too heavy. On its Restructuring & Liability Management page, Rothschild & Co describes recapitalizations and debt restructurings, including debt-for-equity swaps, liability management exercises, formal proceedings such as US Chapter 11, private credit restructurings, distressed M&A and sovereign debt restructurings. Its clients are companies, funds, creditors and governments. Among the deals it highlights are the debt restructurings of Altice France (€25bn, 2025) and Casino (€8.1bn, 2024).
The job also exists for governments. Shadi El Hamalawi, OctoFin's founder, did an internship in Sovereign Advisory at Global Sovereign Advisory from January to June 2025, working on sovereign debt restructurings.
Debt advisory: advising the borrower
Debt advisory sits on the borrower's side. In its Global Financing Solutions business, Rothschild & Co helps clients design their capital structure, access financing markets and get the best terms, whether through bank debt, bonds, private placements, institutional loans, debt funds or hybrid capital. Its argument: independence lets it consider every structure and every provider of debt "without conflict or preference". Lazard files debt advisory under capital structure advisory. The difference with a bank's leveraged finance team fits in one sentence: one underwrites the debt it structures (BNP Paribas uses the word "underwriting"), the other presents itself as independent of the lenders.
Where each bank files these teams
From one firm to the next, the teams don't carry the same name. When you search for offers, type these titles too.
| Firm | How it organizes its teams | Source (read on October 28, 2026) |
|---|---|---|
| Barclays, Paris | Capital Markets division: Debt Capital Markets, Risk Solutions Group, Equity Capital Markets, Leveraged Finance, Syndicate | 2027 Capital Markets off-cycle internship offer |
| BNP Paribas, New York | Global Banking, Corporate Finance: M&A (Unified Sectors Advisory), Leveraged Finance, Equity Capital Markets | 2027 analyst offer |
| Lazard, London | Financial Advisory: M&A and strategic advisory, Restructuring, Capital Structure Advisory (including Debt Advisory and ECM), Private Capital Advisory, Growth Capital Advisory | 2026 recruitment FAQ |
| Rothschild & Co | Global Advisory, including M&A and Strategic Advisory, Global Financing Solutions, Restructuring & Liability Management, Global Markets Solutions and Sovereign Advisory | Global Advisory page |
A neighboring job: transaction services
Transaction services isn't an investment banking job: its teams work in audit and advisory firms, such as KPMG and BDO, which describe themselves that way on their French websites, and they carry out the financial due diligence on a purchase or a sale. On the same sale, the investment bank runs the process; the transaction services team checks the numbers the price rests on. The job is described, with a worked due diligence, in our guide to transaction services.
Banquier d'affaires vs chargé d'affaires: don't mix them up
It isn't the same job. According to France Travail's sheet C1203, the chargé d'affaires bancaires looks after a bank's business clients, offers them financial solutions in line with the bank's commercial policy, negotiates contract terms and knows how to "put together and decide on a financing application". France Travail says the job is open from three to five years of higher education. The banquier d'affaires advises on a deal: selling, buying, raising capital.
Investment banks in Paris, by category
Here are the main families of firms, each named the way the source names it, with the firms that source cites. It isn't a ranking: for the order, go back to what each ranking measures, above.
| Category, in the source's words | Firms cited | Source (read on October 28, 2026) |
|---|---|---|
| "The big American banques d'affaires based in Paris" | Goldman Sachs, Morgan Stanley, JP Morgan, Citi | La Tribune, September 7, 2026 (subscribers only, opening readable) |
| Banque de financement et d'investissement, or CIB (corporate and investment banking) | Crédit Agricole CIB, "the corporate and investment bank of the Crédit Agricole Group"; SG Corporate & Investment Banking in Mergermarket's rankings; Natixis CIB in Crack-It's; BNP Paribas, which speaks of its "Corporate & Institutional Banking" activities | Crédit Agricole CIB's website; Mergermarket; Crack-It; BNP Paribas offer |
| "Independent": independent advisers | Rothschild & Co, "The global independent adviser"; Lazard, "an independent advisory firm"; Evercore, which La Tribune counts among "the independent boutiques" | Rothschild & Co and Lazard pages; La Tribune |
| "Mid-market", "small and mid cap", "TPE-PME-ETI" | Transaction R&Co, Rothschild & Co's mid-market business in France; Largillière Finance, an "independent group" advising on small- and mid-cap M&A; the advisers in Fusacq's small- and mid-cap ranking, such as Clairfield International, Septentrion Finance or Eurallia Finance | Rothschild & Co's Global Advisory page; Largillière Finance offer; Fusacq |
| Audit and advisory firms, which Mergermarket ranks among its "financial advisors" | KPMG Corporate Finance (81 deals in France in 2025); BDO (31). Mergermarket also ranks PwC (40) and Ernst & Young (24) among its financial advisors | Mergermarket, France ranking by deal count; KPMG calls itself an "audit and advisory firm", BDO an "accounting, audit and advisory firm" (websites read on October 30, 2026) |
The Paris banker interviewed by Mergers & Inquisitions draws the same map in his own words: a market that is "definitely more of a mix", where all the bulge bracket banks have a presence, next to the large French banks (BNP Paribas, Société Générale, Crédit Agricole CIB and Natixis), elite boutiques (Lazard, Rothschild, Messier Maris) and European banks with Paris-based teams (Santander, BBVA, UniCredit, HSBC). He adds that many mid-market deals involve private equity firms and family offices.
One term comes up without a list: on its restructuring page, Rothschild & Co contrasts its independent advice with that of the "bulge bracket banks", without naming them, and none of the sources read for this page lists the bulge bracket banks present in Paris: we don't give one. The employers behind M&A internship offers, with what they say about themselves, are in our guide to the M&A analyst.
What French law says: “banque” is a license, “banque d'affaires” a trade
In 1945, a category of bank
The law of December 2, 1945 on the nationalization of the Banque de France and the large banks set out three categories: deposit banks, banques d'affaires and long- and medium-term credit banks (article 4). In the version in force until 1984, deposit banks made loans and took sight and term deposits from the public, with stakes limited to 20% of the capital of companies other than banks, financial institutions or companies needed for their operations. Banques d'affaires, for their part, had as their main business, besides lending, taking and managing stakes in existing or new businesses (article 5). Both articles were repealed by Law No. 84-46 of January 24, 1984 (article 94), with effect from July 25, 1984.
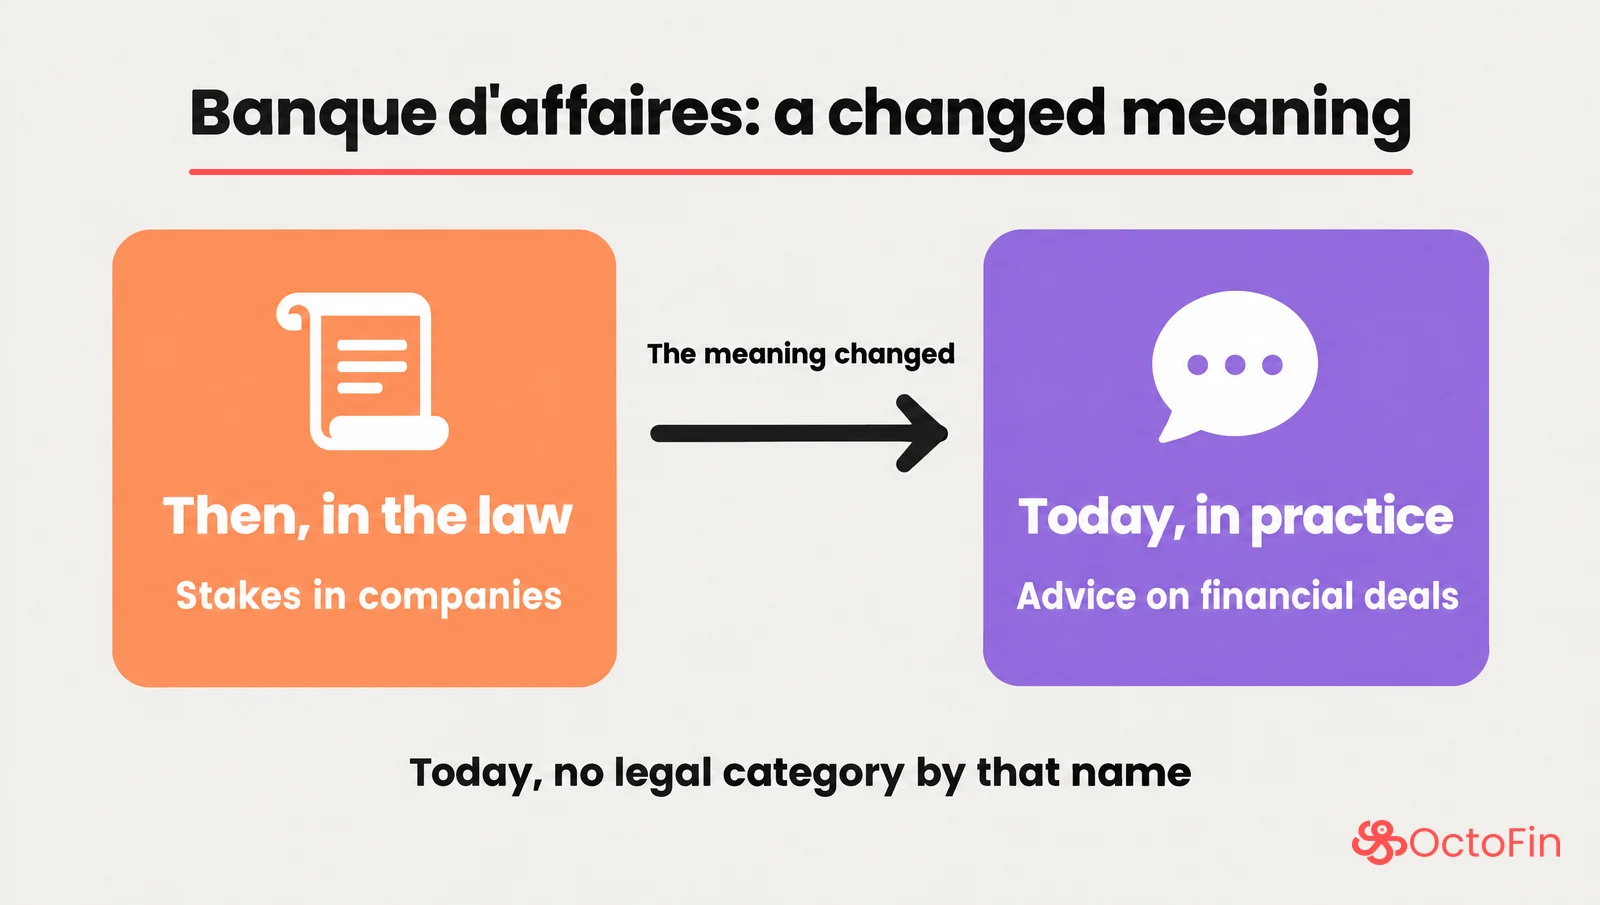
So the meaning has changed. In the 1945 law, as it stood until 1984, a banque d'affaires was defined by its stakes in companies; today, usage defines it by its advice. The Vernimmen glossary still mentions stakes: a banque d'affaires may take some in companies, to sell them later at a gain.
Today, “bank” is a license
The Monetary and Financial Code licenses credit institutions in five categories: bank, mutual or cooperative bank, specialized credit institution, credit and investment institution, municipal credit bank (article L. 511-9). None is called banque d'affaires. A licensed bank can carry out all banking operations, meaning taking repayable funds from the public, lending and banking payment services (article L. 311-1). Advising companies, for its part, is one of the related operations a credit institution may also carry out: advice on financial management, financial engineering and services that help companies start and grow (article L. 311-2, I, 5°).
The Code also protects the status. Any business other than a credit institution or a financing company is forbidden to use a name, a corporate name, advertising or expressions suggesting it is licensed as one, or to create confusion on the point (article L. 511-8). The text doesn't mention the word "banque": it targets any expression that would suggest a license.
In an interview, if you're asked "what is a banque d'affaires?", answer with the trade: advising on financial deals. If the follow-up is about the difference with a deposit bank, you have the 1945 law and what became of it.
How to get into investment banking in France
The internship
The rules, durations and dates are in two separate guides, so we don't repeat them here. Our guide to the off-cycle internship in investment banking covers the definition, the French legal rules, the minimum intern pay and dated offers; our M&A internship recruiting calendar gives, bank by bank, the deadlines and start dates. The Paris banker interviewed by Mergers & Inquisitions in 2015 sums up recruiting in France as being "all about off-cycle internships", with assessment centers less common than in London. He speaks of internships lasting 6 to 12 months, but in France an internship can't exceed 6 months at the same employer per academic year: the rule is explained in our off-cycle guide. If you're aiming at ECM, DCM or leveraged finance, also look at capital markets programs, like Barclays' in Paris, which covers those teams and lasts 3 to 6 months.
Language and schools
For an international candidate, language is the first question. The same M&I interviewee says you definitely need French, but that banks also want candidates with good English, because so many deals are cross-border. On schooling, the Apec lists a five-year degree (Bac+5): a master's in corporate finance or financial engineering, an engineering school, or a business school with a major in finance and accounting, accounting, tax law or business law. The M&I interviewee describes two common routes: a one-year specialized master's, or a full Grande école degree of two to three years. Internship offers also state the school, level and experience they expect: those of Lazard, BNP Paribas CIB and Investec Advisory are compared in our guide to the M&A analyst.
The interview
Technicals revolve around accounting, valuation, the DCF and the LBO: our investment banking interview questions cover them, with answers written to be said out loud, our walk me through a DCF answer is worked with numbers, and you can practice the LBO by hand with our paper LBO example. If you're aiming at leveraged finance, LBO debt has to be clear: ranking, maturity, the difference between mezzanine and high yield.
The ladder, from analyst up
For its London office, Lazard describes a typical path: about three years as an analyst, then three to four years as an associate, before moving up to vice president (VP) "and beyond". The analyst rotates through several sector teams and can specialize in a sector at associate level (2026 recruitment FAQ). For France, the Apec says junior hires start with financial analysis, modeling and due diligence; the M&A advisory banker role itself requires at least 7 years of experience, and beyond 15 years come the largest clients and management responsibility.
Titles vary. On its careers site, Rothschild & Co groups, for instance, "Assistant Director/Vice President/Principal" into one grade. Above VP, none of the sources read for this page describes the roles one by one: ask the bankers you meet. For later in your career, the Apec lists among the possible moves for an M&A advisory banker the roles of chief financial officer, financial analyst or senior banker.
Shadi El Hamalawi, OctoFin's founder, went through these recruiting processes as a candidate: Spring Intern at Nomura in London in March 2024, then intern analyst in Investment Banking at Greenhill in Paris, from July to December 2024.
Frequently asked questions
What is investment banking?
Advising clients on their financial deals and carrying them out: selling or buying a company (M&A), raising equity (ECM) or debt (DCM, leveraged finance, debt advisory), restructuring debt (restructuring). Lazard describes its advisory business this way: M&A and strategic advisory, restructuring, capital structure advisory, private capital advisory. An investment bank adds financing: Barclays speaks of "financial advisory, capital raising, financing and risk management services" (pages read on October 28, 2026). In France, the advisory side is called banque d'affaires.
What is the difference between an investment bank and a deposit bank in France?
The law of December 2, 1945, in the version in force until 1984, separated them: the deposit bank made loans and took sight and term deposits from the public; the banque d'affaires had as its main business, besides lending, taking and managing stakes in companies. That split was repealed in 1984. Today, a licensed bank can carry out all banking operations (article L. 511-9 of the Monetary and Financial Code), and advising companies is one of the related operations it may also carry out (article L. 311-2). In everyday use, the banque d'affaires is the advisory firm; the deposit bank, the one that takes deposits and lends.
What are the top investment banks in France?
It depends on what you measure. In 2025, in France, Goldman Sachs came first by value of deals advised on and Rothschild & Co by number of deals, according to LSEG (Les Echos, December 31, 2025) and to Mergermarket (rankings as of January 3, 2026). In Crack-It's perception ranking (updated October 26, 2026), the top three are Goldman Sachs, J.P. Morgan and Rothschild & Co. In the small- and mid-cap market, Largillière Finance tops Fusacq's 2025 ranking, which counts the revenue of the companies acquired. The best one for you is the one in your segment: reread "How to read the league tables" before you draw up your list.
Do you need to speak French to work in investment banking in Paris?
The Paris banker interviewed by Mergers & Inquisitions says yes: you definitely need French, and banks also want good English because so many deals are cross-border (interview published in February 2015). It's one banker's account, from 2015, not a rule written by the banks: check each offer, which states the languages it requires.
How much does an investment banking intern earn in Paris?
We don't give a general figure, for lack of a reliable source: we found no primary, dated source on the pay of a junior investment banker in France. The Apec publishes a range taken from job ads, but for a role that requires at least 7 years of experience, without saying over what period. For an internship, one offer gives a precise marker: Barclays shows a €30,000 annual base salary, on a full-time-equivalent basis, for its Capital Markets off-cycle internship in Paris, excluding other pay (offer read on October 28, 2026). It's neither an average nor the salary of a permanent analyst job. The same caution applies to hours: no source read gives a figure, and Lazard only writes that hours in investment banking tend to be longer than in some other professions. The French legal minimum for intern pay is calculated in our guide to the off-cycle internship.
What degree do you need to become an investment banker in France?
A five-year degree (Bac+5), according to the Apec: a master's in corporate finance or financial engineering, an engineering school, or a business school with a finance and accounting major, accounting, tax law or business law. The Paris banker interviewed by Mergers & Inquisitions adds that candidates either complete a full Grande école degree or a one-year specialized master's.
Keep practicing
To get into investment banking in France, the technicals have to come without effort: the bridge, multiples, the DCF, the LBO. OctoFin prepares you for interviews in M&A, private equity, DCM, ECM, leveraged finance and sovereign advisory. Its 11 chapters and 57 lessons cover, among other things, accounting, the DCF, the Merger Model and the M&A process; for practice, there are more than 1,000 questions (multiple-choice, flashcard or open-ended) and more than 1,300 reports of real interviews, to see what banks actually ask. Plans and pricing are on the home page: see pricing. OctoFin doesn't offer one-to-one coaching: for a mock interview with an investment banker, a human coach is the better fit.